
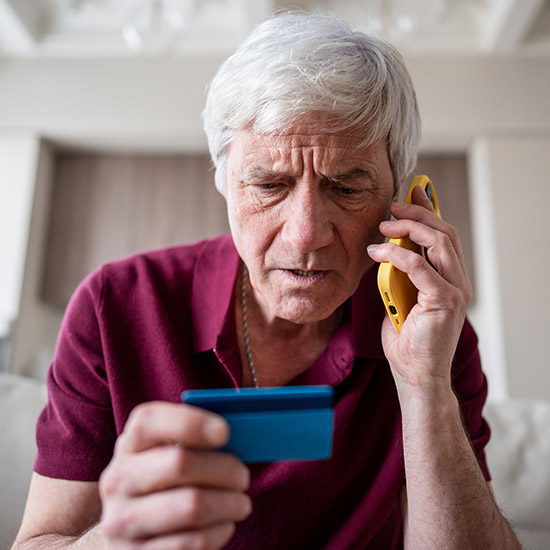
Elder abuse continues to be a crisis that often goes unnoticed until the damage is done. While elder abuse can take many forms — physical, emotional, and neglect — financial exploitation remains the most prevalent and fastest-growing. For banks, this is not only a social issue but also a matter of risk management, regulatory compliance, and customer trust.
As trusted stewards of consumers’ money, financial institutions are uniquely positioned to detect, prevent, and disrupt elder financial abuse across every payment channel — often before losses become irreversible.
The Financial Reality of Elder Abuse
Financial exploitation of older adults costs victims billions of dollars each year, with many incidents going unreported due to embarrassment, fear, or dependence on the abuser. Unlike traditional fraud, elder exploitation is frequently authorized; the customer believes the transaction is legitimate.
Common scenarios appear across core payment rails:
- Wires: An older customer is pressured to send an urgent wire to a scammer posing as a government agency, contractor, or family member in distress.
- ACH: Repeated outbound ACH transfers are set up to a “new investment opportunity” or caregiver, slowly draining an account over time.
- Checks: Large checks are written to unfamiliar individuals, charities, or businesses, sometimes with altered payees or endorsements.
- Real-Time Payments (RTP/FedNow): Customers are coached to move funds instantly to avoid “account closure” or “fraud investigation,” leaving no recovery window.
- Debit Cards: Daily ATM withdrawals or point-of-sale activity spikes after a new person gains access to the card or PIN.
These transactions may look valid on the surface, but the context tells a different story.
Why Financial Institutions Are a Critical Line of Defense
Banks and credit unions are often the only third party with visibility into changing financial behavior. Front-line staff and operations teams may observe:
- Sudden use of unfamiliar payment types (e.g., first-time wires or real-time payments)
- Uncharacteristic urgency, secrecy, or scripted responses
- A new individual directing or controlling the customer’s transactions
- Payment requests that conflict with the customer’s historical activity
For example:
- A member who has never sent a wire insists on sending one immediately and refuses to answer basic questions.
- An elderly customer who typically writes small checks begins issuing large checks weekly to a “helper.”
- A debit card shows repeated ATM withdrawals just below daily limits after a family member moves in.
These moments represent critical intervention opportunities. How staff members respond can determine whether funds are protected or permanently lost.
Regulatory Expectations and Safe Harbor Considerations
Regulators increasingly expect financial institutions to play an active role in identifying and responding to elder financial exploitation. Key considerations include:
- Suspicious Activity Reports (SARs): Elder abuse and exploitation are recognized SAR categories, regardless of whether the transaction was authorized.
- State Reporting Requirements: Many states mandate or encourage reporting suspected exploitation to Adult Protective Services or similar agencies.
- Safe Harbor Protections: Federal and state laws often protect institutions and employees who report suspected abuse in good faith.
A well-designed program allows institutions to act decisively while balancing customer autonomy, privacy, and legal obligations.
Building an Effective Elder Financial Protection Program
Strong elder abuse prevention programs are practical, actionable, and embedded into daily operations — not buried in policy manuals.
1. Channel-Specific Staff Training
Training should help employees understand how exploitation manifests differently across payment types. (See “Red Flags by Payment Type” later in this article for specific examples.)
Empowered staff are more likely to pause, question, and escalate concerns appropriately.
2. Clear Escalation, Holds, and Referral Procedures
Employees should know:
- When transaction delays or holds are permitted
- How to escalate concerns about fraud, BSA/AML, or management
- How to engage customers respectfully without accusation or alarm
Speed is especially critical for real-time payments and wires, where funds may be unrecoverable within minutes.
3. Cross-Functional Collaboration
Effective programs break down silos between:
- Fraud and financial crimes teams
- BSA/AML and compliance
- Legal and risk management
- Branch, call center, and member service staff
Information sharing ensures suspicious patterns are identified early and addressed consistently.
4. Smart Use of Technology
Transaction monitoring, velocity controls, and alerts can flag unusual behavior — but technology is most effective when paired with trained employees who understand customer context.
Red Flags by Payment Type: What Staff Should Watch For
Elder financial exploitation often looks different depending on the payment rail. Recognizing channel-specific red flags can help staff pause transactions and escalate concerns before losses occur.
Wires
- First-time or infrequent wire activity, especially for urgent or high-dollar amounts
- Customer appears coached, evasive, or unwilling to answer basic questions
- Requests to wire funds to overseas or unfamiliar recipients tied to emergencies
ACH
- New outbound ACH transfers to individuals or businesses with no prior relationship
- Increasing frequency or dollar amounts of recurring ACH payments
- Customer unable to clearly explain the purpose of the ACH debit or credit
Checks
- Large checks written to unfamiliar individuals, charities, or contractors
- Altered payees, suspicious endorsements, or requests for cashier’s checks
- Sudden increase in check usage inconsistent with historical behavior
Real-Time Payments (RTP/FedNow)
- Extreme urgency tied to alleged fraud, account closure, or government action
- Customer insists funds must be sent immediately and cannot wait
- Requests to move funds after hours or outside normal banking patterns
Debit Cards
- Spikes in ATM withdrawals or cash advances, often just below daily limits
- Customer reports someone else is “helping” manage their card or PIN
- Repeated declined transactions followed by successful withdrawals
Turning Awareness into Action: A Call to Action for Financial Institutions
Banks should consider:
- Staff Training: Refresh training annually with real-world examples tied to wires, ACH, checks, debit cards, and real-time payments.
- Policy and Procedure Reviews: Ensure elder financial exploitation guidance is clear, current, and aligned with state and federal expectations.
- Community Outreach: Partner with senior centers, caregivers, and local organizations to educate older adults on common scams and safe banking practices.
Protecting older customers is not only a regulatory expectation — it is a trust imperative. By recognizing warning signs and acting with confidence and compassion, financial institutions can help prevent life-altering losses and preserve dignity.
Let’s use our position in the financial system to detect, disrupt, and prevent elder financial abuse across every payment rail.
Because safeguarding money also means safeguarding people.
To help your financial institution be at the forefront of preventing elder financial abuse, we created a staff job aid and scripts you can download, print, and provide to your team. Download the “Responding to Suspected Elder Financial Exploitation” job aid and script.
Chrissy Terry is Vice President of ePayAdvisors, a subsidiary of ePayResources. She has over 20 years of experience in financial institution support operations and holds Accredited Faster Payments Professional (AFPP), Accredited Payments Risk Professional (APRP), National Check Professional (NCP), and Accredited ACH Professional (AAP) credentials. Contact Chrissy via email at cterry@epayadvisors.com.